Investor overview · Data room open to qualified investors under NDA
The operating layer for oil and gas. Raising the next round.
NDA · 48-hour reply
How it fits together
One backbone. Two operating products.
- Customer's existing stackNothing rips. Nothing replaces.
- P2
- Quorum
- Peloton
- Enertia
- Maximo
- SAP
- AVEVA PI System
- AVEVA
- Cygnet
- Esri GIS
- ION SCADA
- The brainWorkSync DataHub
Included in your WellOPS or FlowSync subscription.
39 integrations - Two operating productsWellOPS and FlowSync
- Operations · 5,000+ wells
- WellOPS · Willie, AI field specialist
- Engineering · 2,000+ miles modeled
- FlowSync · Taylor, AI engineer agent
DataHub
Pre-built integrations to the SCADA, ERP, CMMS, and accounting systems the operator already runs. Included in your WellOPS or FlowSync subscription.
FlowSync
The engineering side. Build models from PDFs. Simulate on live data. Studies in minutes. Taylor inside.
WellOPS
The operations side. The ranked plan in every truck cab by 6 AM, scored by cash flow and risk. Willie inside.
What WorkSync delivers
Two sides. One operating layer.
Operations
more free cash flow
Same crew. Four-week pilot. Cash-flow and risk-aware daily work plans in every truck cab by 6 AM.
Measured across 5,000+ wells in live deployments
Engineering
miles of pipeline modeled
Hydraulic model builds go from weeks of manual effort to minutes of verification. Engineers stop rebuilding models and start running studies.
Deployment account
The proof, by the numbers
The operating layer for oil and gas.
- 5,000+wells live across our customer baseMeasured across live deployments
- 15%more free cash flow on the same crewMeasured in live deployments, four-week pilot
- 35%fewer miles driven, same production coverageMeasured deployment figure
- Weeks → Minuteshydraulic model builds, manual effort to verificationDeployment account
Upstream producers and midstream pipeline operators, on gathering and transmission, run the same backbone with different modules on top.
Charge when the metric moves. Not before.
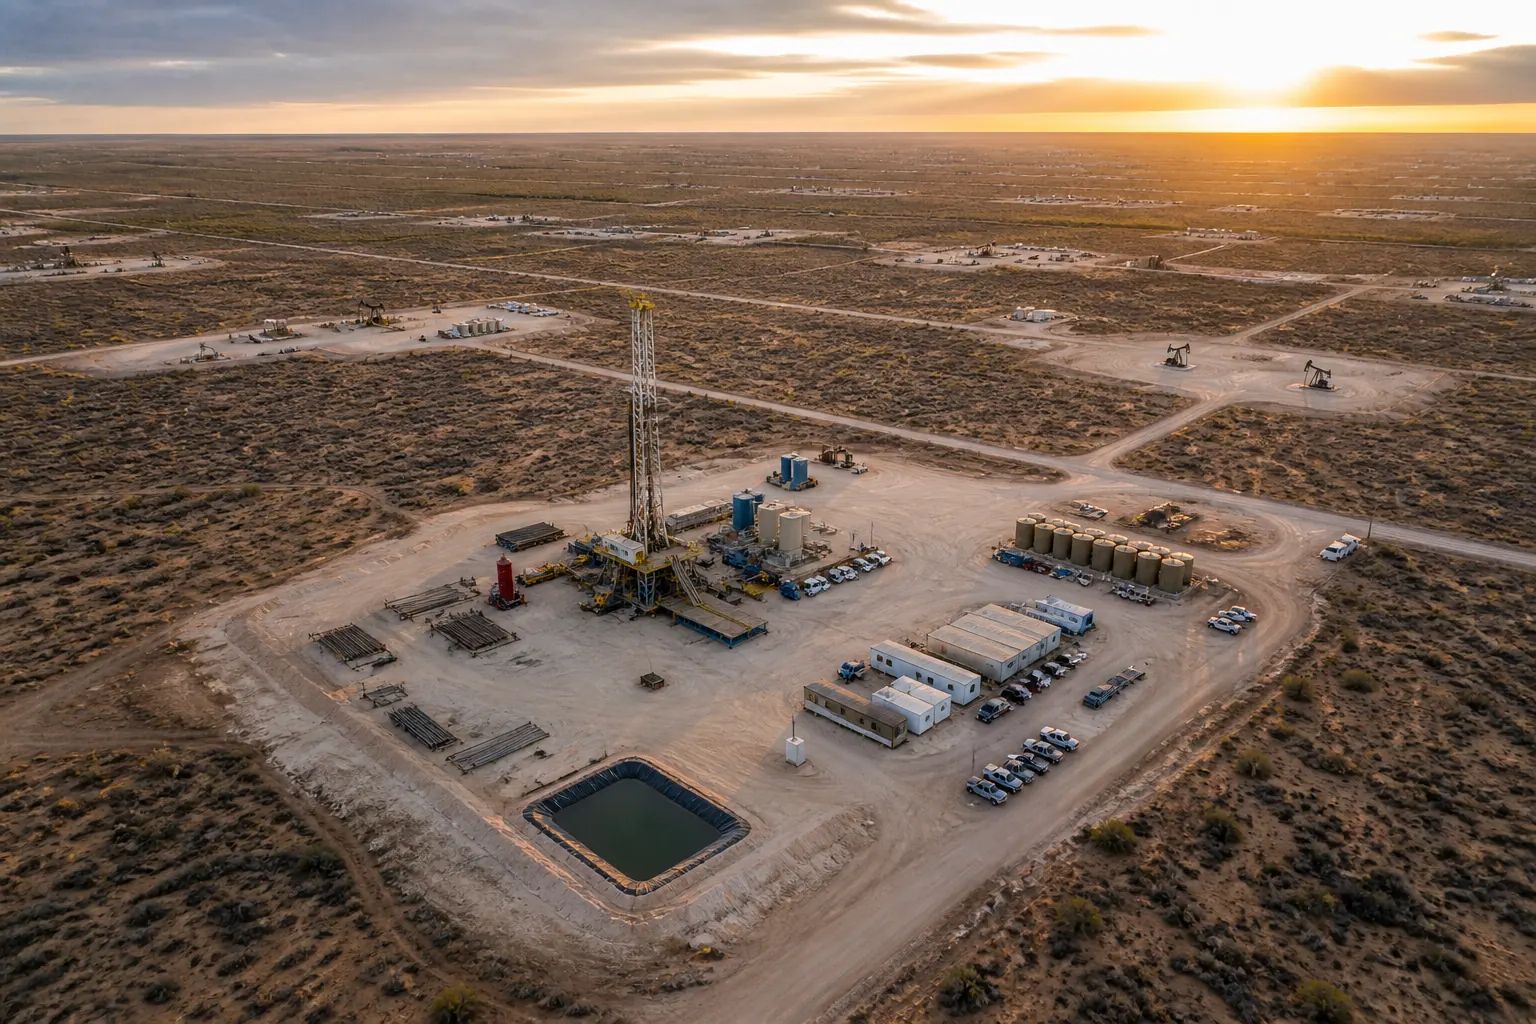
WorkSync is not another system to log into. It is the operating floor the whole field day runs on.
Investment thesis
Four reasons WorkSync becomes the operating layer.
- 01
The intelligence layer is a category.
Every distributed energy operator runs the same stack: SCADA, ERP, CMMS, GIS, production accounting. None of them tell a foreman what to do tomorrow morning. The thin software tier that does is a category, not a feature. We are building it. - 02
The buyer pain is acute and measurable.
Operating cost is set by what the field actually does each day, and the order that work happens in is still chosen by hand, lease by lease, every morning. That gap has a number on it. WorkSync moves free cash flow 15 percent on the same headcount and the same wells inside a four-week pilot (measured in live deployments). - 03
Agentic AI is a 24-month gap, not a 24-month feature.
Stanford AI Index: inference costs down 99 percent 2018 to 2025. Deloitte 2026: 67 percent of finance leaders integrating agentic. Operators who deploy now compound the lead. Operators who wait spend the next decade catching up. - 04
The moat is the DataHub, not the model.
Models commoditize. Pre-built integrations to P2, Quorum, Maximo, SAP, AVEVA PI System, AVEVA, Cygnet do not. The WorkSync DataHub is the work no competitor wants to redo, and we include it in your WellOPS or FlowSync subscription.
Inference is 99 percent cheaper. Free cash flow moves 15 percent on the same crew. The arbitrage window is open right now.
Stanford AI Index 2025 · WorkSync deployment figure
Defensibility
Five things competitors will not redo.
- 01
Pre-built oilfield-native integrations
P2, Quorum, Peloton, Enertia, Maximo, SAP, AVEVA PI System, AVEVA, Cygnet, ION, SCADA Pack, and the rest of the named connector library. Two-year head start on anyone trying to enter without it. - 02
Two named AI agents shipping today
Willie (field) and Taylor (engineering) run on the same DataHub. Productized agents with operator-facing UX, not lab demos. Built to make your best engineers and pumpers faster. Not to replace them. - 03
Risk-shared commercial model
Impact Guarantee: four-week pilot with license fees only when the metrics move. We charge when the metric moves, not before. Carrying the risk on our side is what shortens the enterprise sales cycle. - 04
Outcome data flywheel
Every deployment captures what happened, what we predicted, and what moved. Models retrain nightly. The longer customers run, the wider the gap to a Year 1 entrant. - 05
OT-grade security from day one
SOC 2 Type II in progress (report targeted Oct 30, 2026), IEC 62443-aligned, on-prem LLM option. Built for the operators who cannot use the public cloud and the IT teams who will not approve another SaaS perimeter risk.
Market
6 of 10of the highest-value upstream AI use cases are daily field operations. That is the layer WorkSync builds.
McKinsey, August 2026
McKinsey ranked upstream AI use cases by value in August 2026 and put roughly $230 billion of full-potential annual value on the industry, with the top ten carrying close to half of it. Six of those ten happen on a lease, on a shift, with a truck and a crew and a pump. Those are McKinsey’s dollar figures, not WorkSync revenue figures, and the classification of the six as field operations is ours.
Our own market model, sized bottom-up, is in the data room.
ESP optimization
WellOPS
Gas lift optimization
WellOPS
Predictive maintenance
WellOPS, Willie
Rod pump optimization
WellOPS
Schedule optimization
WellOPS, the 6 AM plan
Supply chain
DataHub
Figures are McKinsey’s published full-potential values (McKinsey & Company, August 2026). The full ranking, the arithmetic across these six, and the reconciliation of the two different $65 billion figures in circulation are set out on the Upstream AI Value Map.
Why now
The window is closing.
- 99%drop in inference costStanford AI Index, 2018 to 2025
- 67%finance leaders integrating agenticDeloitte 2026
- Under 20%of AI deployments measure the value they producedMcKinsey, August 2026
Operators who deploy field intelligence in 2026 compound the lead across three years of cost takeout, capital efficiency, and safety performance. Operators who wait spend the next decade trying to close the gap.
WorkSync is what an operator picks when the window starts to close.
The plan
Where the next 24 months of investment go, in order.
- 01
Go-to-market expansion
Direct coverage across the producing basins we already deploy in, plus the midstream pipeline vertical. A larger field deployment crew, because deployment speed is the constraint, not demand. - 02
Product and AI agent development
The next agents on the roadmap for midstream operations and regulatory reporting. Continued investment in the DataHub connector library, which is the part nobody wants to redo. - 03
Customer success and deployment science
Repeatable four-week pilot mechanics and the outcome telemetry that proves the metric moved. The Impact Guarantee only works if the measurement is instrumented before the pilot starts.
Round mechanics, the split of the investment across these priorities, valuation guidance, ARR, NRR, gross margin, burn, runway, our bottom-up market model, and customer references are in the data room. Available to qualified investors under NDA.
The ask
The operating floor your competitors are on. Now.
Founded by Michael Atkin, P.Eng, on the conviction that the daily decision about what the field works on next is the most valuable unmodeled decision in the business. Leadership across upstream production engineering, midstream pipeline hydraulics, OT cybersecurity, and enterprise AI deployment. Detail and bios in the data room.